
LFAM
Large format additive manufacturing, or LFAM, is the idea of 3D printing very large, life-size parts, and it is a principle rather than a single technology, showing up differently depending on the material (image courtesy: Xenia Materials).
In polymers, it is a standalone segment of material extrusion, generally defined by the ability to produce single parts larger than one cubic meter, though photopolymerization and polymer powder bed fusion are increasingly used for large parts too. In metals, the equivalent scale comes mainly through directed energy deposition (DED) and increasingly through powder bed fusion systems that have grown large by adding lasers rather than by changing process. Both branches solve the same problem, building large parts efficiently, with different hardware, materials, and trade-offs.

Polymer LFAM
Polymer LFAM splits along mechanical architecture, Cartesian and gantry-based versus robotic, and along material type, since some systems run composite pellets exclusively while others also handle unfilled, recycled, or biosourced polymers.
Robotic extrusion, mounting a print head on an industrial robot rather than a gantry, has been emerging as the preferred solution due to its versatility. Segment leader Caracol, founded in Milan in 2017, built its early systems on Kuka robots with LEHVOSS materials and recycled plastics, later adding Maire Tecnimont’s MyReplast compounds, its Heron platform and High Versatility extruder in 2023, and an Airtech Dahltram resin partnership. CEAD has run its Flexbot Comau robot under Siemens motion control since 2019 and qualified Dahltram resins across the line in 2021.
Robotic LFAM has no inherent size limit, since a robot arm on rails can extend almost indefinitely. The largest commercial example, CEAD’s Flexbot, built for the UAE’s Al Seer Marine, prints parts up to 36 meters long and 4 meters wide. It should be noted that Ai Build, a UK software company founded in 2015, supplies the AiSync CAM platform many robotic LFAM systems run on, however other solutions also exist.
Gantry systems move a print head along fixed linear axes and, because many share genuine CNC architectures, are often sold as hybrids that alternate between printing and milling, fiber placement, tape laying, inspection, and trimming. The segment traces to 2014, when Cincinnati Incorporated launched the first commercial LFAM system under the BAAM name before later exiting the market. CMS, an Italian builder, is today’s rising name, with its Kreator system, developed with Germany’s Fraunhofer Institute, pairing five-axis milling with Screw Extrusion Additive Manufacturing, or SEAM. Thermwood, a US company with over 50 years as a CNC builder, holds a strong position through its LSAM platform, sold into aerospace and automotive tooling. Italy’s Belotti and Breton and Germany’s KraussMaffei round out the field.
Every polymer LFAM machine runs on pellets rather than filament, since converting polymer into filament adds cost that makes no sense at these volumes. Most also print fiber-reinforced composite rather than unfilled plastic, because enclosing a build space several meters across is impractical, so machines operate in open air, where chopped carbon or glass fiber prevents warping as large parts cool unevenly, while also cutting weight and sometimes material cost. Fused Granular Fabrication, or FGF, is a version that uses enclosed chambers, allowing companies like JuggerBot 3D, GINGER Additive, and Titan Robotics, which was acquired by 3D Systems in 2023, to use unfilled, recycled, and biosourced polymers that open-frame machines usually cannot. In 2023, China’s Kings 3D entered the segment with five machines plus a hybrid system, spanning an enclosed 800 x 600 x 800 mm FGF800 up to an open 3,500 x 2,400 x 1,000 mm FGF2435.
Metal LFAM
In metals, DED applies a laser, electron beam, or electric arc to melt and deposit powder or wire in layers, and is the most industrialized branch of metal AM since most variants evolved from welding and cladding processes bolted onto CNC-style motion control. Laser DED melts feedstock as it exits the nozzle, cooling at up to 5,000°C per second under inert gas; vendors split between AM-native builders like Optomec and BeAM, now part of AddUp, and machine tool majors, chiefly DMG Mori, whose LASERTEC line leads the segment on build volume and hybrid capability.
Wire arc additive manufacturing, WAAM, draws the most attention and is the oldest process by far, essentially 1920s arc welding adapted to build parts layer by layer rather than join two pieces of metal. It produces near net shape parts that are then machined to finish, operating in a window of roughly 1 mm resolution and 1 to 10 kg per hour deposition, between slower laser DED and faster but less accurate plasma and electron beam systems. Commercial hardware is recent despite the old underlying process, and WAAM’s appeal is delivering L-DED-like results on wire feedstock priced at a tenth of atomized powder, opening applications like maritime propellers, automotive frames, and even bridges, at the cost of needing subtractive finishing and facing vendors still short on high-level industrial track record. AML3D leads the segment with its ARCEMY platform and certified defense, energy, and maritime work, followed by MX3D, which has matured from research demonstrations to certified heavy-industry production, and Gefertec and WAAM3D, with their Arc603/3DMP and RoboWAAM/WAAMCtrl systems respectively. Among newer entrants, Caracol is notable for bringing its large-format composites reputation into metal AM in 2024 with Vipra AM, offered as the plasma-arc Vipra XQ for precision aerospace and energy parts and the cold-metal-transfer Vipra XP for higher-throughput aluminum and nickel work.
Electron beam AM, EBAM, is narrower still, with Sciaky the only relevant vendor, melting wire at 3 to 11 kg per hour, sometimes blending two alloys in dual wire feed systems, backed since 2014 by parent Phillips Service Industries and a track record in aerospace and defense parts, though the single-supplier market and high capital cost remain constraints.
Set against these, metal laser powder bed fusion has scaled up differently, by adding lasers rather than changing process. Where early LPBF systems ran a single laser over a modest plate, builders including EOS, SLM Solutions, Nikon SLM Solutions, Trumpf, and China’s BLT and Farsoon now offer four-, eight-, and twelve-laser systems on larger plates, working in parallel to close LPBF’s throughput gap against DED while keeping the precision and surface finish that made powder bed fusion the default for complex, high-value metal parts.

It’s officially autumn, which in the additive manufacturing industry means one thing: Formnext is right around the corner. Ahead of the Frankfurt-based additive manufacturing industry event, sector leaders are already…

Hyperion Systems and Inspire Robotics have signed an agreement to install a TitanCell, Hyperion’s containerized large-format additive manufacturing system, in Timor-Leste. The unit is due to be commissioned later this…

Robotic additive manufacturing company Caracol, which has headquarters in Milan, Italy and Austin, Texas, has become the newest member of America Makes. The announcement, made during IMTS 2026, will strengthen…

Researchers at Oak Ridge National Laboratory (ORNL) have developed an extrusion system that combines multiple 3D printing extruders into a single high-output stream, using specially designed nozzles. Aimed at a…

Next week at the International Manufacturing Technology Show (IMTS) in Chicago, AM experts and enthusiasts will have lots to see. Among these showcases will be the 11-foot-tall Aires Tide, a…

Welcome to our first eBook dedicated exclusively to large-format additive manufacturing (LFAM). This particular topic is unique in that its focus is not on a specific type of technology or…

Francesco Furlani drove a three-wheeled Piaggio Ape TM 703 from Italy to Nordkapp, Norway’s North Cape. He covered more than 4,500 kilometers across nine countries at speeds of just 40…

This summer, European energy company E.ON opened a new office at the historic Tacheles art center in Berlin. Dubbed the House of New Energy, the new location is no ordinary…

When we talk about large-format additive manufacturing (aka LFAM), we are not talking about a singular technology. Rather, the term encompasses any 3D printing technology capable of printing big parts,…
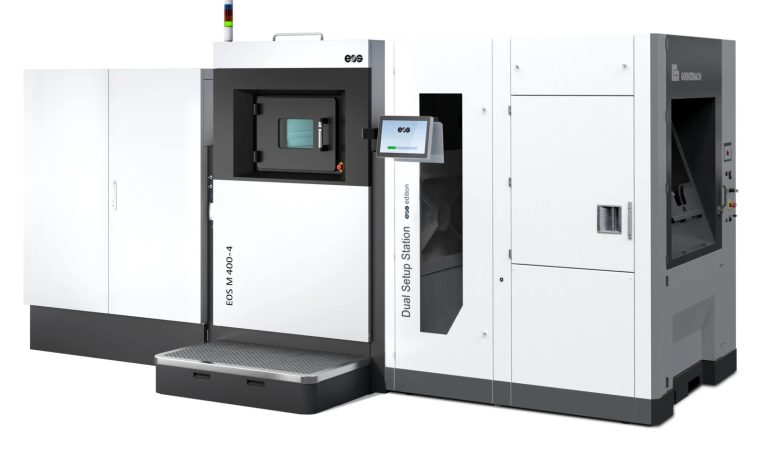
AnyShape is expanding its metal additive manufacturing capacity with two EOS M 400-4 systems, targeting aerospace and defense programs that require large, complex components built to repeatable, industrial-grade quality. Both…


